

Non-Resident Directors
TAX ADVISER & ACCOUNTANT | HMRC AUTHORISED AGENT | COMPANIES HOUSE ACSP
London | Serving individuals and companies in the UK and overseas
25+ Years' Experience | ICO Registered | HMRC AML Supervised
A UK company with a director based overseas carries the same statutory obligations as any other: a UK registered office, Companies House filings, HMRC returns and fixed deadlines. Distance does not extend a deadline, and letters sent to the registered office are treated as received.
Administration of UK companies with overseas directors

What determines your position
The registered office must be an appropriate address. Documents sent there must come to the attention of a person acting on the company's behalf and be capable of being acknowledged. A company must also maintain a registered email address.
Directors must verify their identity. Every director and person with significant control must verify their identity with Companies House, directly or through an authorised corporate service provider. Without it, filings can be rejected.
Deadlines run regardless of location. Annual accounts are due nine months after the year end, with a longer period for the first accounts. Corporation Tax is payable nine months and one day after the end of the accounting period, and the return is due within twelve months.
The company is UK tax resident. A company incorporated in the UK is generally UK tax resident. Where it is managed from abroad, the position under the relevant double tax treaty should be reviewed.
The director's own position is separate. Director's fees and salary paid by a UK company are generally taxable in the UK under most double tax treaties. Dividends and other income follow different rules depending on residence.
Records must be kept in the UK format. Accounting records must support the accounts and returns, and be retained for at least six years. Bookkeeping on MTD-compatible software keeps the records consistent with HMRC's requirements.
Late filing has automatic consequences. Companies House and HMRC charge penalties automatically for late accounts and returns, and persistent failures can lead to the company being struck off.
The administration of UK companies with overseas directors forms part of the practice's work. Official correspondence is received, reviewed and explained, statutory deadlines are monitored, and the company is represented before HMRC and Companies House. All matters are handled in confidence.
The services we provide
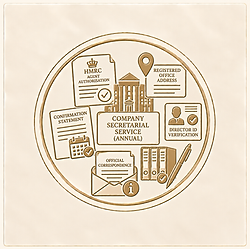
Company secretarial service (annual)
HMRC agent authorisation, registered office address, director identity verification, the annual confirmation statement, and the receipt and explanation of official correspondence.

Incorporation
Formation of a UK limited company, with articles, share structure and persons with significant control established from the outset.

HMRC
registrations
Set-up of HMRC and Companies House accounts, and registrations for Corporation Tax, PAYE and VAT where required.

Bookkeeping and payroll
Records maintained on MTD-compatible software, and payroll for directors and staff.

Accounts and Corporation Tax
Annual accounts filed with Companies House, and Corporation Tax calculated and returned to HMRC.

Changes and filings
Changes to directors, PSCs, share capital and company details, filed with Companies House.
The scope of work is agreed individually, according to the company's needs.
From enquiry to administration
01
ENQUIRY
Provide the company details, or the proposed structure for a new company.
02
DUE DILIGENCE
Directors and persons with significant control are verified in line with anti-money laundering regulations.
03
TERMS
The scope and fees of the engagement are confirmed in writing.
04
AUTHORISATION
Agent authorisation is completed, the registered office is transferred and official correspondence is redirected.
05
ADMINISTRATION
Deadlines are monitored, correspondence is handled and filings are made throughout the year.
